Asset Finance Australia
Work vehicles, trucks, machinery or office equipment. PFGA helps you compare lenders and find a finance structure suited to your cash flow.
Australia-wide · Access to multiple lenders
Asset Finance Built Around Your Business
We compare banks and specialist lenders, then structure your finance around your cash flow.
Work Vehicle & Ute Finance
Finance vans, utes and fleet vehicles, new or used, with repayments that suit your cash flow.
Truck & Trailer Finance
Fund prime movers, rigids and trailers with repayments that suit your contracts.
Plant & Machinery Finance
Excavators, tractors, graders, cranes and dozers, financed around your project cash flow.
Office & Commercial Equipment Finance
Upgrade technology, fit-outs and commercial equipment without tying up working capital.
Chattel Mortgage
Own the asset from day one with fixed repayments. Ask your accountant about tax treatment.
Hire Purchase & Finance Lease
Compare ownership, balloon payments and end-of-term options.
Asset Finance for Australian Businesses
PFGA is a business finance broker helping Australian business owners since 1998. We compare banks, credit unions and specialist lenders to find vehicle and equipment finance that suits your cash flow, whether you’re in Townsville, Cairns, Mackay or anywhere in Australia.
What can you finance?
Work vehicles, trucks, trailers, excavators, tractors, graders, cranes, dozers and office equipment. Each asset type has its own lender rules on age, deposit and term.
Which finance structure suits you?
A chattel mortgage and hire purchase both spread the cost over fixed monthly repayments. The asset often acts as security. Ownership and tax treatment differ, so speak with your accountant.
Why finance instead of paying cash?
Paying outright can tie up money needed for wages, stock and materials. Finance keeps working capital available for seasonal changes and long projects.
Why use a broker?
Each lender has different policies. We explain what they look for and compare options before you apply. Fee and commission disclosure
Why PFGA
Your Business Deserves More Than One Bank’s Opinion
As an Australian asset finance broker, we help business owners compare lenders for work vehicles, trucks, trailers and machinery. Different lenders have different rules on asset age, deposits and approvals. What one declines, another may consider.
- Experienced advice. We explain what lenders look for, from chattel mortgage and hire purchase to finance lease options.
- Multiple lenders. Banks and specialists, not one policy, so you can compare equipment finance options before you apply.
- Tailored structures. Business asset finance that protects your working capital, with repayments built around your cash flow.
- Support to settlement. We manage the application for commercial vehicles, plant and equipment finance from start to finish.
Ready to Explore Your Options?
Speak with PFGA before approaching a lender.
1800 574 055 · [email protected] · ABN 89 114 404 090 · ACL 386814
Asset Finance Without the Runaround
1. Tell us about the asset
What you’re buying, the price, new or used.
2. We review lending options
We compare lenders and structures for your situation.
3. We arrange your finance
We manage the application through to settlement.
Real experiences from Australian businesses we’ve helped finance and grow.
Our Recent Reviews
Frequently Asked Questions
What is asset finance?
Asset finance is a way to fund business assets such as vehicles, machinery and equipment, instead of paying cash upfront. The asset usually acts as security, and you repay the cost over a fixed term. It can help you keep working capital available for wages, stock and projects. PFGA compares lenders and structures to find one that suits your cash flow.
What assets can I finance?
Common assets include work vehicles, utes and vans, trucks and trailers, excavators, tractors, graders, cranes, dozers, and office and commercial equipment. Each asset type has its own lender rules on age, deposit and term. Tell us what you’re buying and we’ll check which lenders may suit it.
Which finance structure suits my business?
It depends on whether you want ownership from the start, how you want to manage cash flow, and what you want to happen at the end of the term. Chattel mortgage gives you ownership from day one, hire purchase transfers ownership after the final payment, and an operating lease means you never own the asset. Tax treatment differs, so speak with your accountant. PFGA explains your options and compares them side by side.
What’s the difference between a finance lease and hire purchase?
With a finance lease, the lender owns the asset, and you generally have the option to take ownership by making a final balloon payment. With hire purchase, the lender owns the equipment until you make the final payment, and ownership then transfers to you. The right choice depends on what you want to do with the asset at the end of the term.
What happens at the end of the finance term?
It depends on your structure. At the end of a hire purchase, ownership transfers to you, while at the end of a finance lease you’ll generally need to deal with a residual or balloon payment. If you can’t pay a balloon, you may need to refinance or sell the equipment. It’s important to plan for this at the start, and PFGA helps you do that.
How long can the loan term be?
Terms vary by structure, lender and the age of the asset. Chattel mortgages commonly run over one to seven years, often with a balloon payment at the end to lower monthly costs. A longer term can lower your repayments, but you may pay more interest overall. We’ll show you the trade-offs.
Can I finance a fleet of vehicles?
Yes. You can finance several vehicles, either under one arrangement or as separate agreements. Lenders look at your total exposure, so how it’s structured matters. PFGA can help plan your fleet finance around your cash flow and when you expect to replace vehicles.
Do I need a deposit for asset finance?
Not always. Hire purchase may not require a deposit, while a deposit is optional with a chattel mortgage. Requirements vary by lender, asset and your business, and a larger deposit can improve your options. We’ll check what suits your situation before you apply.
Does it cost anything to use PFGA for asset finance?
PFGA explains how we’re paid, and any fees that may apply, before you proceed, so there are no surprises. You can read more in our fee and commission disclosure. To talk through your situation, call us on 1800 574 055 or book an appointment.
Ready to Explore Your Options?
Speak with PFGA before approaching a lender.
1800 574 055 · [email protected] · ABN 89 114 404 090 · ACL 386814
Latest Articles
Business Debt Consolidation Loan Australia: Restructuring Loans
A Business Debt Consolidation Loan Australia combines debts into one repayment. We explain cash flow benefits, costs and refinancing options for you. ...more
Business Finance
November 09, 2026
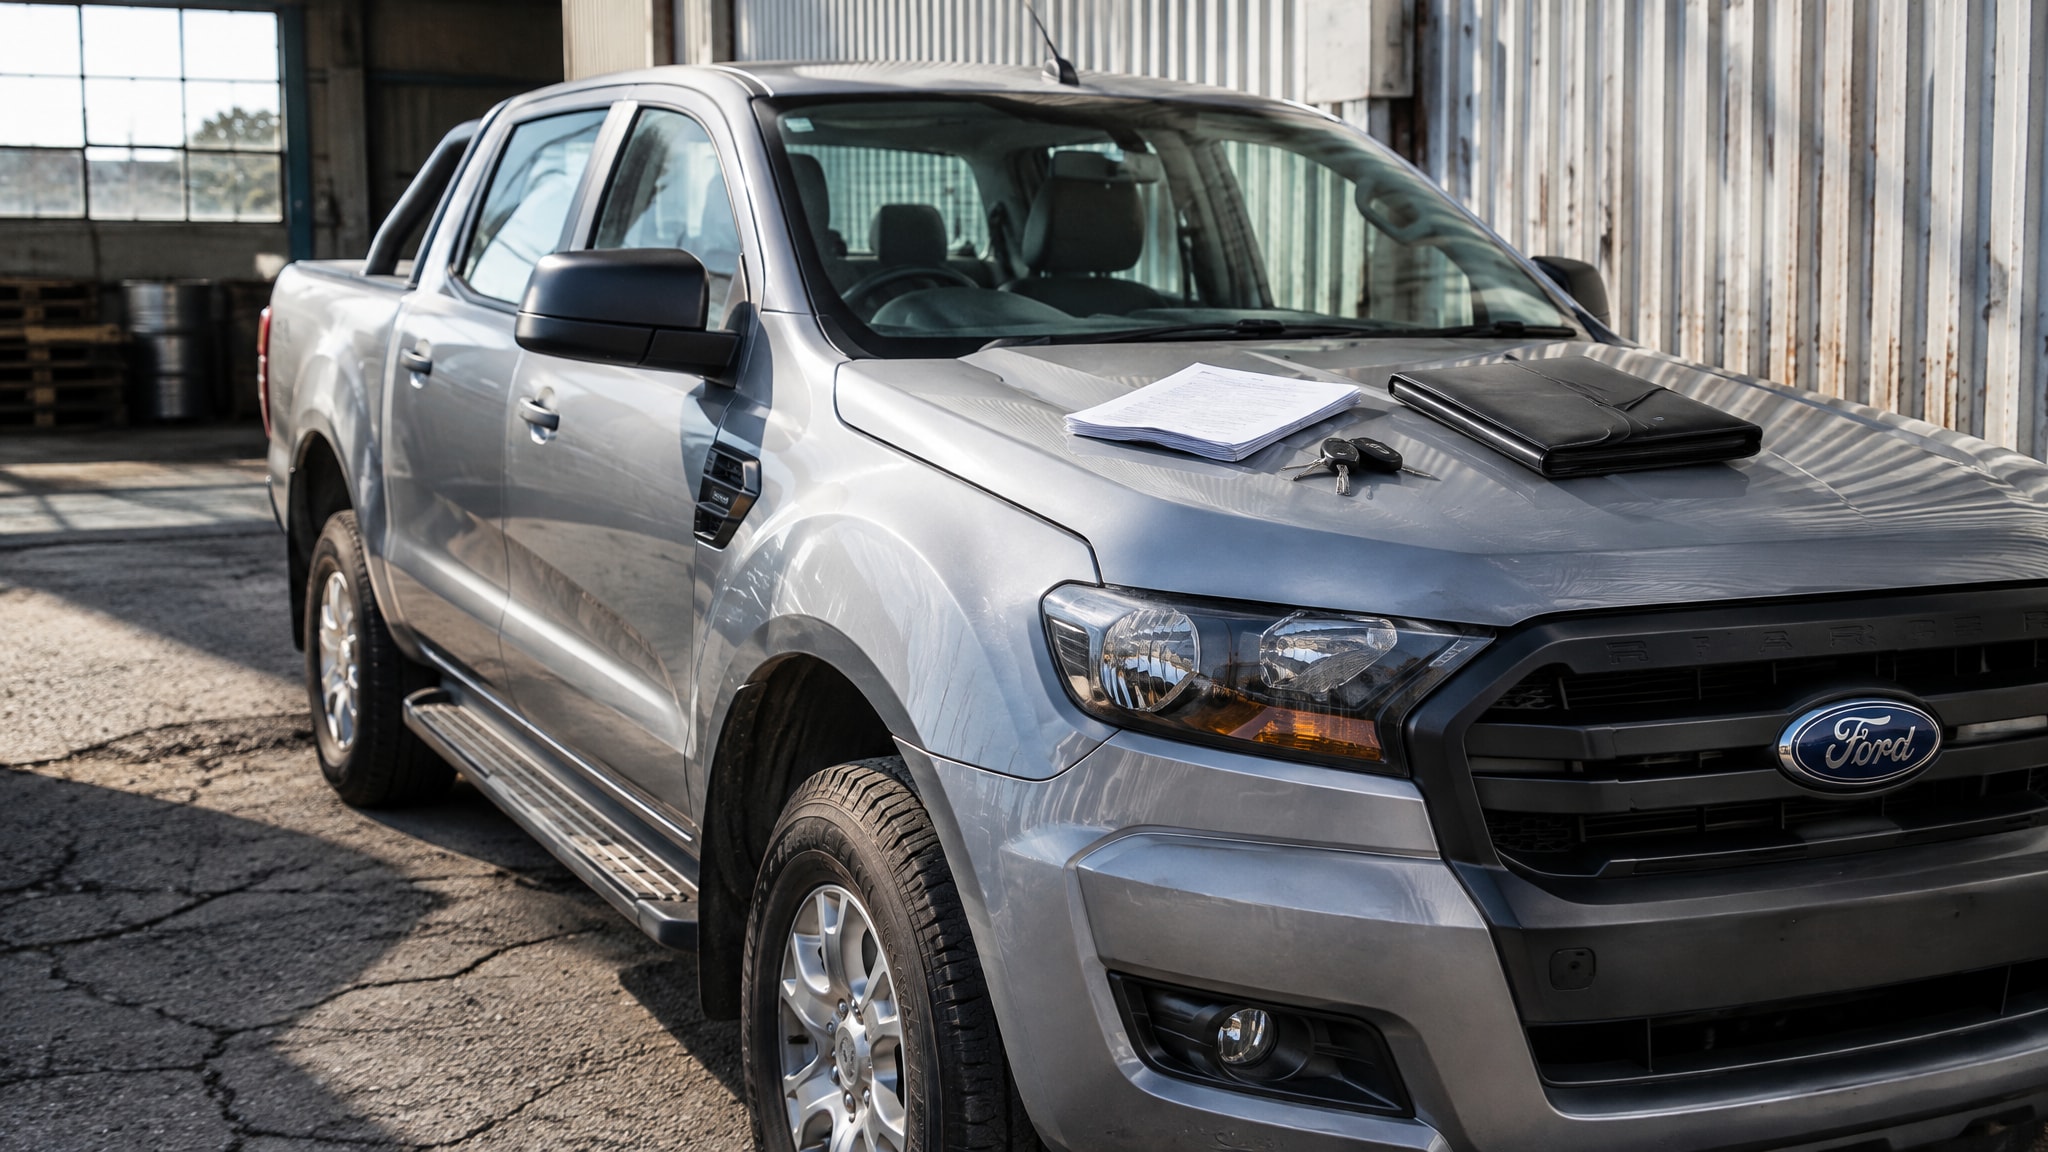
Commercial Vehicle Finance for Business: Structuring Loans
Structure commercial vehicle finance for business correctly. We explain chattel mortgages, leases, GST and borrowing capacity before you apply. ...more
Business Finance
November 05, 2026
Fast Business Loan Approval Australia: Realistic Timeframes
Understand fast business loan approval in Australia. We explain realistic timeframes, lender speeds and how to prepare your file for quicker funding. ...more
Business Finance
November 02, 2026
Unsecured Business Loan No Property Security Explained
Need an unsecured business loan with no property? We explain limits, risks and eligibility to help you make informed finance decisions. ...more
Business Finance
October 29, 2026
Business Acquisition Loan Broker Australia: Structuring Funding
A Business Acquisition Loan Broker in Australia structures funding to match asset mix and lender policy, protecting your credit file from declined applications. ...more
Business Finance
October 26, 2026
Business Vehicle Finance: Aligning Loans With Cash Flow
Align business vehicle finance with your cash flow cycle. We help structure repayments around seasonal revenue to protect working capital and growth. ...more
Business Finance
October 23, 2026


Key Service Areas
Connect
Toll Free: 1800 574 055
Email: [email protected]
Hours: Mon - Fri 8:30am - 5:00pm AEST
Townsville | Brisbane | Sydney | Melbourne | Adelaide
Premium Mortgage Management Pty Ltd ABN: 89 114 404 090 Australian Credit Licence #386814
© 2026 Premium Finance Group Australia. All rights reserved. | Privacy Policy